




Processing...
How We Helped Get Insurance Approval for a New Roof
W Hennessey St, Bloomington, IN, US, 47403
Description
I. Introduction
When door knocking in neighborhoods affected by storms, homeowners often identify roof damage. Offering a free roof inspection for potential hail damage can be a proactive step in determining the need for a roof replacement.
II. Storm Damage Roof Inspection
Conducting a thorough storm damage roof inspection is crucial for securing insurance approval. Here’s how to do it effectively:
- Take photos of the entire house from multiple angles to document the condition of the roof.
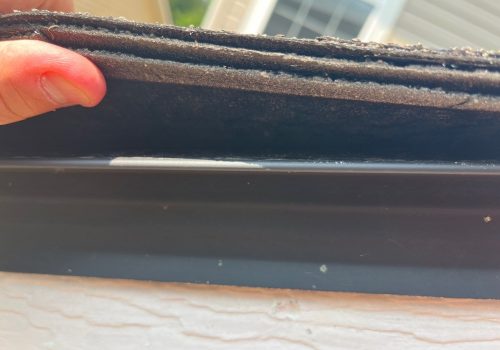
- Confirm the number of layers of shingles present on the roof, as this can affect replacement costs.
- Check for wind-damaged shingles by lifting each shingle and documenting the damage with a chalk line.
- Inspect for hail damage and circle any affected areas with chalk for clear visibility.
- Summarize the findings regarding the number of wind and hail damages per slope of the roof.
- Document collateral damage on soft metals such as box vents, gutters, etc. to provide comprehensive evidence of damage.
- Determine if the damage warrants an insurance claim based on the inspection findings.
III. Understanding Insurance Coverage
It’s essential to understand the insurance coverage related to roof replacement:
- Homeowners insurance typically covers roof replacement due to storm damage.
- Specific endorsements and policies may provide additional coverage; check your specific policy details.
Be aware of common exclusions and limitations:
- Wear and tear is usually not covered.
- Lack of maintenance can also lead to denied claims.
IV. Filing an Insurance Claim
To initiate a claim, follow these steps:
- Contact your insurance agent or claims person to report the damage.
- Submit the roof inspection report as part of your claim documentation.
Schedule a meeting with the insurance adjuster to assess the damage further.
V. Working with Adjusters
Preparation is key when meeting with an insurance adjuster:
- Prepare documentation and be ready to discuss the inspection findings.
- Ensure that your roofing sales representative is present during the assessment for support.
- Know what to expect during the assessment process, including detailed questioning about the damage observed.
- Communicate effectively with the adjuster to clarify any misunderstandings.
VI. Dealing with Denied Claims
If your claim is denied, understand the reasons for denial and take the following steps:
- Review the denial letter to identify the specific reasons for the decision.
- Consider steps to appeal the denied claim, gathering further evidence if necessary.
- If needed, engage a public adjuster or attorney to help navigate the appeals process.
VII. Finalizing Approval and Replacement
Once you receive approval, understand that:
- The approval process can vary; remain in contact with your insurance company.
- It is preferred to work with the contractor who helped you secure the approval.
- Coordinate effectively between your insurance company and contractor to schedule the roof replacement.
VIII. Conclusion
To recap, securing insurance approval for a roof replacement requires a proactive approach, including thorough inspections, understanding coverage details, effective communication with adjusters, and being prepared for potential denials. Staying informed throughout the process is vital to ensuring a smooth experience.
FAQs
1. What are the first steps in getting insurance approval for a roof replacement?
The first steps include identifying roof damage, conducting a thorough storm damage inspection, and consulting your insurance policy.
2. How can I prove the extent of roof damage to my insurance company?
Taking extensive photos from multiple angles and documenting damage with chalk during your inspection can help provide evidence of damage.
3. What should I do if my insurance claim is denied?
If your claim is denied, review the denial reasons, appeal the decision, and consider seeking help from a public adjuster or attorney.
4. Is wear and tear covered under a standard homeowners insurance policy?
Generally, wear and tear is not covered by homeowners insurance; claims are usually focused on sudden damages from incidents like storms.
5. Why is it important to have a roofing sales representative during the adjuster’s visit?
Having a roofing sales representative present can provide expert insight, support your findings, and help ensure that all damage is adequately documented.</p
Comments

Share this Project


Recent Projects


Indianapolis
Quick Menu
Services
Follow Us On Social
Modern Roof is a dba of Modern Companies, LLC